

Redwire (RDW) is an integrated space and defense technology company supplying spacecraft components, digital engineering, autonomous aircraft, sensors and mission systems. The Edge Autonomy acquisition broadened the portfolio from space infrastructure into combat-proven uncrewed aircraft, creating more exposure to defense budgets and international demand. That expansion increases Redwire's scale, though it also raises integration, program-execution and capital-allocation risk.
The latest quarter showed that the combined platform can grow rapidly. RedWire Q2 2026 revenue rose 89.6% to a record $117.1 million, gross margin improved to 27.8% from negative 30.9%, and contracted backlog reached $542.1 million. Adjusted EBITDA remained negative at $3.2 million, so the investment case depends on whether backlog conversion and operating leverage can turn record demand into consistent profit.
The RDW stock forecast for 2026 now centers on two competing views:
- The defense scale and backlog case: a 1.42x book-to-bill ratio, $542.1 million backlog and expanding Stalker and Penguin demand could support sustained growth and positive adjusted EBITDA.
- The integration and profitability case: slower program execution, fixed-price cost pressure or continued losses could prevent revenue growth from reaching per-share earnings.
This guide breaks down the RDW stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on Redwire’s August 5, 2026 Q2 2026 earnings release, quarterly filing and market data through September 11, plus how to trade RDW stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Redwire Investors to Know in September 2026
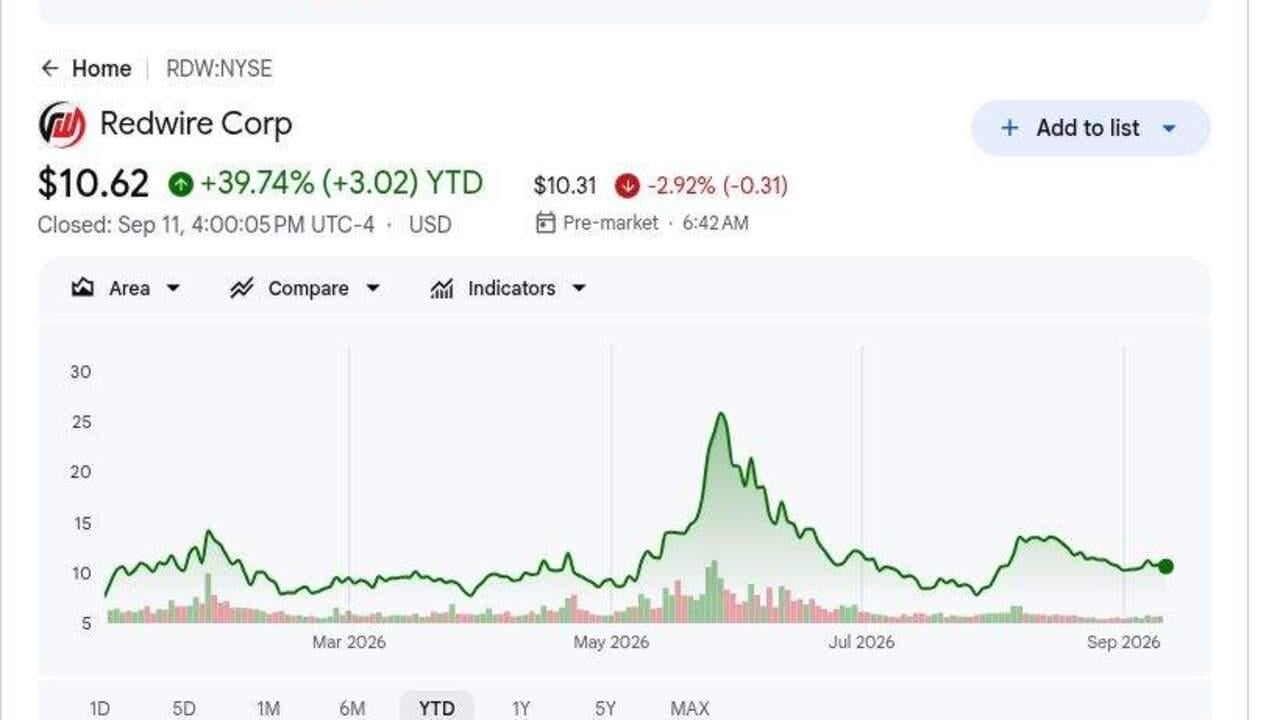
- The $10.62 September 11 close left RDW up about 39.4% in 2026: The gain reflects stronger defense demand, though shares had retreated substantially from their May high. A $14 analyst consensus and $24 Street high imply upside only if backlog converts and margins continue improving.
- Q2 revenue reached a record $117.1 million, up 89.6%: The result exceeded the $107.1 million consensus by about $10.0 million. Edge Autonomy and broader program activity increased scale, giving Redwire more revenue across space and airborne defense markets.
- Gross margin improved 58.7 percentage points to 27.8%: The comparison with negative 30.9% a year earlier is the clearest operational improvement. Adjusted EBITDA also narrowed by $24.2 million to a $3.2 million loss despite $12.5 million of research and development spending.
- Contracted backlog reached $542.1 million with 1.42x book-to-bill: Backlog increased about $130.8 million from year-end, and bookings exceeded revenue during Q2. The figures support stronger visibility, though contract timing and execution determine how quickly backlog becomes recognized revenue and cash.
- Redwire reaffirmed $450 million to $500 million of 2026 revenue: First-half revenue totaled $214.0 million, leaving $236 million to $286 million for the second half. The range requires continued program execution but does not assume every $542.1 million backlog dollar converts this year.
What Is Redwire (RDW)?
Redwire is an aerospace and defense technology supplier serving civil space agencies, commercial operators and U.S. and allied military customers. Its space portfolio includes solar arrays, deployable structures, avionics, sensors, spacecraft platforms, radio-frequency systems and microgravity research hardware. Edge Autonomy adds Stalker and Penguin uncrewed aircraft, intelligence payloads and autonomous operations. Revenue is generated through product deliveries, engineering services and government contracts with fixed-price, cost-plus and time-and-material structures.
The company's long-term direction connects space infrastructure with autonomous multi-domain defense systems. The U.S. Marine Corps and Army have issued follow-on Stalker Block 30 awards, while Penguin contracts include a multi-year high-eight-figure NATO-country order and a Taiwan Coast Guard program. Redwire also supports NASA missions and partners with Bristol Myers Squibb, Purdue University, Rowan University and Aspera Biomedicines on in-space pharmaceutical research. These relationships diversify demand, though government procurement and launch schedules still shape revenue timing.
Read More: Top Defense Stocks to Buy in 2026: Primes, Missiles, Drones, Space, and AI-Enabled Warfare
Redwire (RDW) Q2 2026 Earnings Overview: Revenue, Operating Scale and Financial Outlook
Redwire delivered record Q2 2026 revenue, positive gross margin and higher backlog, though profitability remained incomplete. Revenue of USD 117.1 million beat the USD 107.1 million consensus by about USD 10.0 million and grew 89.6%, adjusted EPS of negative USD 0.09 beat the negative USD 0.16 estimate, and gross margin reached 27.8%. Contracted backlog rose to USD 542.1 million and management reaffirmed USD 450 million to USD 500 million of full-year revenue, leaving execution and cash conversion as the main tests.
Read More: Redwire (RDW) Q2 2026 Earnings Overview: $117.1M revenue rises 89.6% Drives a 10.35% Price Rally
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q2 2026 revenue |
$107.1M consensus |
$117.1M |
Beat. About $10.0M above consensus and up 89.6% YoY. |
|
Q2 adjusted EPS |
$(0.16) consensus |
$(0.09) |
Beat. Loss was $0.07 narrower than consensus. |
|
Q2 GAAP net loss |
$(97.0)M in Q2 2025 |
$(41.0)M |
Improved. Loss narrowed by $56.0M YoY. |
|
Q2 gross margin |
(30.9)% in Q2 2025 |
27.80% |
Expanded. Margin improved 58.7 percentage points YoY. |
|
Q2 adjusted EBITDA |
$(27.4)M in Q2 2025 |
$(3.2)M |
Improved. Loss narrowed by $24.2M despite $12.5M of R&D. |
|
Q2 book-to-bill |
— |
1.42x |
Positive. Orders exceeded recognized revenue during the quarter. |
|
Contracted backlog |
$411.3M at December 31, 2025 |
$542.1M |
Record. Backlog increased about $130.8M from year-end. |
|
Total liquidity |
$130.2M at December 31, 2025 |
$607.8M |
Strengthened. Liquidity increased 366.9% from year-end. |
|
FY2026 revenue outlook |
Prior $450M-$500M |
$450M-$500M |
Reaffirmed. First-half revenue of $214.0M supports the range. |
- Revenue of USD 117.1 million beat consensus by about USD 10.0 million: The 89.6% increase reflected the larger defense portfolio and stronger program activity. The beat shows demand is converting into reported sales rather than remaining entirely in backlog.
- Adjusted EPS of negative USD 0.09 was USD 0.07 better than consensus: GAAP net loss also narrowed by USD 56.0 million to USD 41.0 million. Redwire remains unprofitable, though higher scale is beginning to reduce loss intensity.
- Gross margin improved to 27.8% from negative 30.9%: The 58.7 percentage-point swing points to much healthier contract economics and acquisition mix. Sustaining positive margins is necessary before revenue growth can support durable cash flow.
- Adjusted EBITDA improved by USD 24.2 million to negative USD 3.2 million: The result included USD 12.5 million of research and development expense. Positive EBITDA is within reach if revenue converts on schedule and program costs remain controlled.
- Liquidity rose 366.9% to USD 607.8 million: The total included USD 557.0 million of cash and restricted cash plus USD 50.0 million of credit availability. The stronger balance supports integration and investment, while term debt fell from USD 90 million to USD 50 million.
Redwire (RDW) 2026 Investment Outlook: $24 Bull Case vs. $8 Bear Case
The following Bull, Base and Bear outcomes are BingX Academy editorial scenarios rather than Wall Street targets. Each range depends on observable operating and financial conditions.
The Bull Case: Strong Defense Demand Pushes RDW Toward $24
The Bull Case assumes the USD 542.1 million backlog converts near schedule, book-to-bill stays above 1.0x and Edge Autonomy expands sales across Stalker, Penguin and Octopus systems. Gross margin remains near or above 27.8%, helping adjusted EBITDA move from a negative USD 3.2 million into positive territory.
A move toward $24 would require full-year revenue near the USD 500 million guidance ceiling, positive adjusted EBITDA and more U.S. or NATO awards. Continued backlog growth and better operating cash flow would strengthen the case.
The Base Case: Steady Backlog Growth Keeps RDW Between $14 and $18
The Base Case assumes Redwire reaches the USD 450 million to USD 500 million revenue range and maintains positive gross margin, while integration and R&D spending keep profit improvement gradual. Space infrastructure and autonomous aircraft both contribute, though contract timing keeps quarterly results uneven.
RDW could trade mainly between $14 and $18 under these conditions. Book-to-bill above 1.0x, stable backlog and adjusted EBITDA near break-even would support the range. Revenue below USD 450 million or gross margin below 25% would weaken the upper end.
The Bear Case: Project Delays Pull RDW Toward $8
The Bear Case assumes customers delay awards or deliveries, backlog converts more slowly and fixed-price programs absorb higher engineering costs. Edge Autonomy integration also takes longer, keeping expenses ahead of the profit contribution from acquired revenue.
A move toward $8 would become more likely if backlog falls below USD 500 million, adjusted EBITDA losses widen from negative USD 3.2 million or management lowers the USD 450 million revenue floor. More equity or debt financing would add further pressure.
RDW Stock Price Forecasts for 2026 By Wall Street Analysts
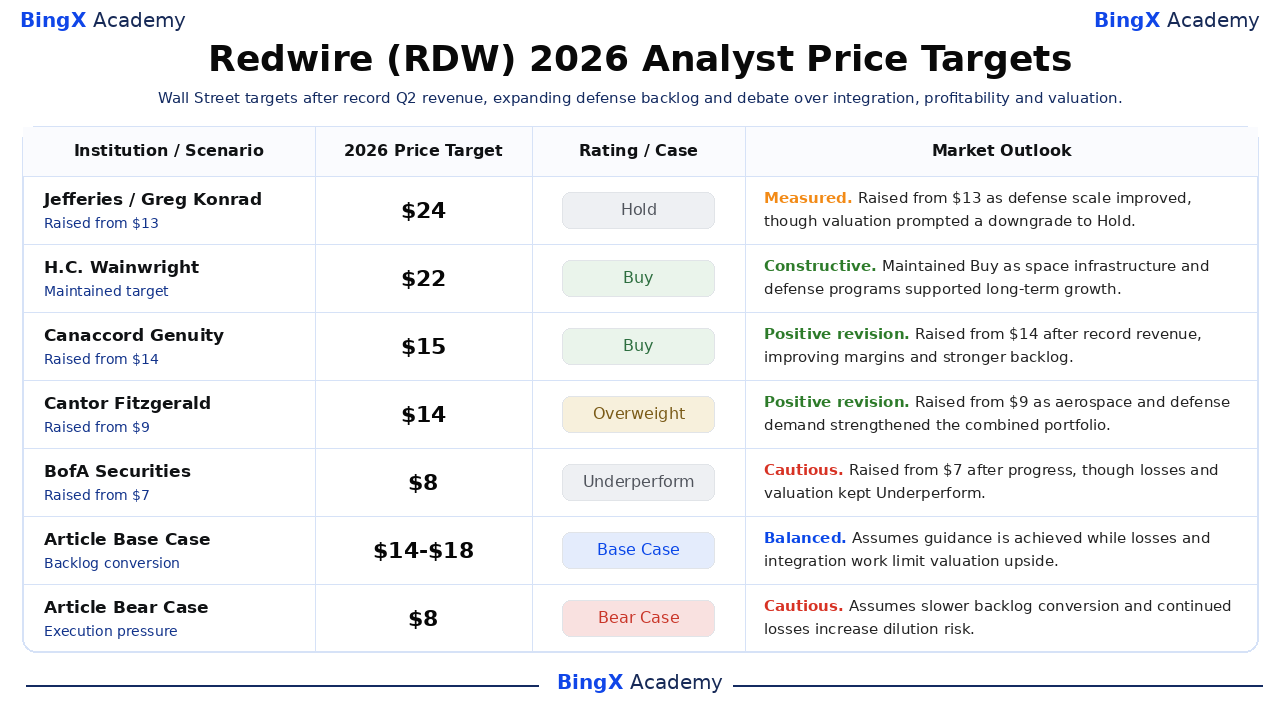
These five dated actions span $8 to $24 and show how Wall Street balances record backlog and defense demand against integration, losses and valuation. They are third-party reference points rather than a single forecast. The final Base and Bear rows are BingX Academy editorial scenarios.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Jefferies |
$24 |
Hold |
Measured. June 1: Raised from $13 as defense scale improved, though valuation prompted a downgrade to Hold. |
|
H.C. Wainwright |
$22 |
Buy |
Constructive. December 23: Maintained Buy as space infrastructure and defense programs supported long-term growth. |
|
Canaccord Genuity |
$15 |
Buy |
Positive revision. August 10: Raised from $14 after record revenue, improving margins and stronger backlog. |
|
Cantor Fitzgerald |
$14 |
Overweight |
Positive revision. August 5: Raised from $9 as aerospace and defense demand strengthened the combined portfolio. |
|
BofA Securities |
$8 |
Underperform |
Cautious. August 31: Raised from $7 after progress, though losses and valuation kept Underperform. |
|
Article Base Case |
$14-$18 |
Base Case |
Balanced. Assumes guidance is achieved while losses and integration work limit valuation upside. |
|
Article Bear Case |
$8 |
Bear Case |
Cautious. Assumes slower backlog conversion and continued losses increase dilution risk. |
How to Trade Redwire (RDW) Stock on BingX
Trade Redwire's defense-order, backlog-conversion and profitability outlook using BingX TradFi and BingX AI tools. Because RDW can react sharply to contract awards, program timing, margins and financing, traders should define both the catalyst and risk limits before entering a position.
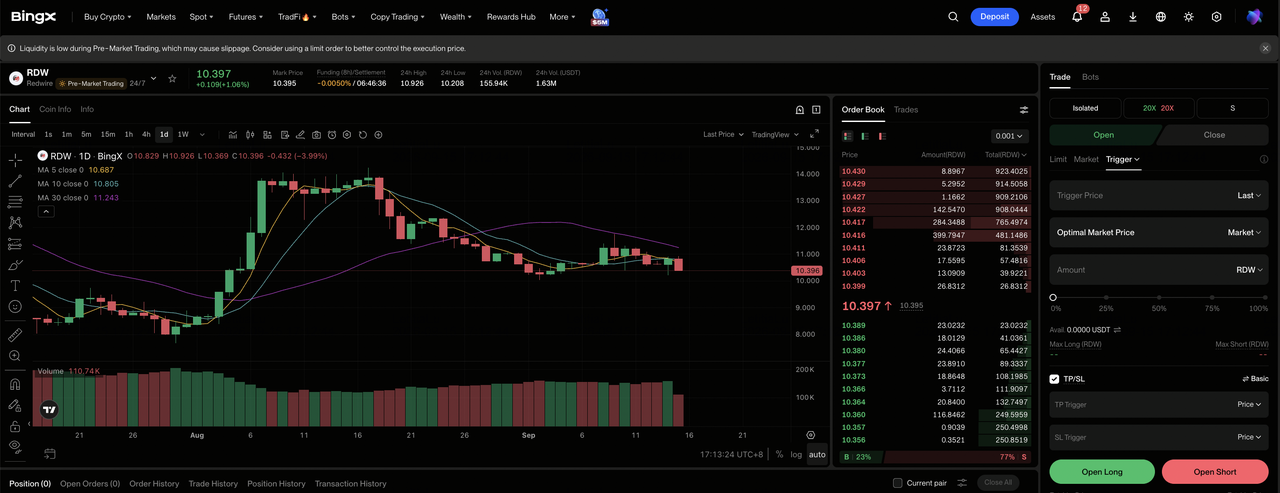
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Redwire (RDW). Search for and select the RDW-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if operating milestones improve and profitability advances. Select Open Short if execution delays or weaker demand reduce expected per-share economics.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. The stock's large 2026 swings show why conservative leverage and clear position sizing are important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. RDW can react quickly to earnings, guidance, contracts, financing and sector conditions.
Top 5 Risks to Watch for Redwire Investors in 2026
Redwire's upside depends on linked contract, integration, customer and financing variables. Each can affect cash conversion or the valuation assigned to every share.
- The $542.1 million backlog may convert slower than expected: Backlog is not revenue and depends on customer funding, milestones and delivery schedules. Delays can move sales and cash receipts into later periods even when contracts remain active.
- Edge Autonomy integration can interrupt the 89.6% growth trajectory: The acquisition expanded revenue and defense exposure, though systems, teams and cost structures must be combined. Missed savings or program disruption could reduce the 27.8% gross margin and delay positive EBITDA.
- Government concentration makes revenue sensitive to budgets: Stalker and Penguin demand includes U.S. military and NATO customers. Continuing resolutions, protests or changing procurement priorities can delay awards and lower the pace at which book-to-bill converts into recognized sales.
- A $3.2 million adjusted EBITDA loss shows profitability remains unproven: The loss improved by $24.2 million but still consumed operating capacity. If research spending and corporate costs grow faster than gross profit, revenue can rise without generating sufficient cash flow per share.
- Capital raises can dilute ownership despite $607.8 million of liquidity: Redwire has strengthened its balance sheet, though acquisitions and capacity expansion remain capital intensive. Future equity issuance can increase the share count and reduce each existing share's claim on eventual earnings.
Final Thoughts: Should You Invest in Redwire in 2026?
Redwire's Q2 results materially strengthened the operating case. Revenue reached $117.1 million, gross margin moved to 27.8% and backlog climbed to $542.1 million. The remaining weakness is profitability, with a $41.0 million GAAP net loss and $3.2 million adjusted EBITDA loss showing that demand has not yet become consistent cash generation.
The Bull Case requires backlog conversion, defense awards and positive adjusted EBITDA to support $24. The Bear Case reflects integration delays, contract pressure and financing risk that could pull RDW toward $8. Conservative traders may wait for revenue near the $500 million guidance ceiling, backlog above $542 million and a positive adjusted EBITDA quarter.
Risk Reminder: Trading and investing in equities like RDW involves a high risk of capital loss. Company execution, market volatility, financing and leveraged trading can produce rapid losses. Conduct independent research before allocating capital.
Related Reading
- Top Space Stocks to Buy Ahead of SpaceX IPO
- Top Defense Stocks to Buy in 2026: Primes, Missiles, Drones, Space, and AI-Enabled Warfare
- Rocket Lab (RKLB) Price Prediction 2026: Can New Rocket and Defense Growth Push RKLB Toward $150?
- Firefly Aerospace (FLY) Price Prediction 2026: Can Launch and Defense Growth Push FLY Toward $55?
- Virgin Galactic (SPCE) Price Prediction 2026: Can Delta Testing Push SPCE Toward $5?
